This week
Common organisation, different presentations: advancing natural capital accounting together
“How could we come up with a common organisation of information irrespective of how we present?”
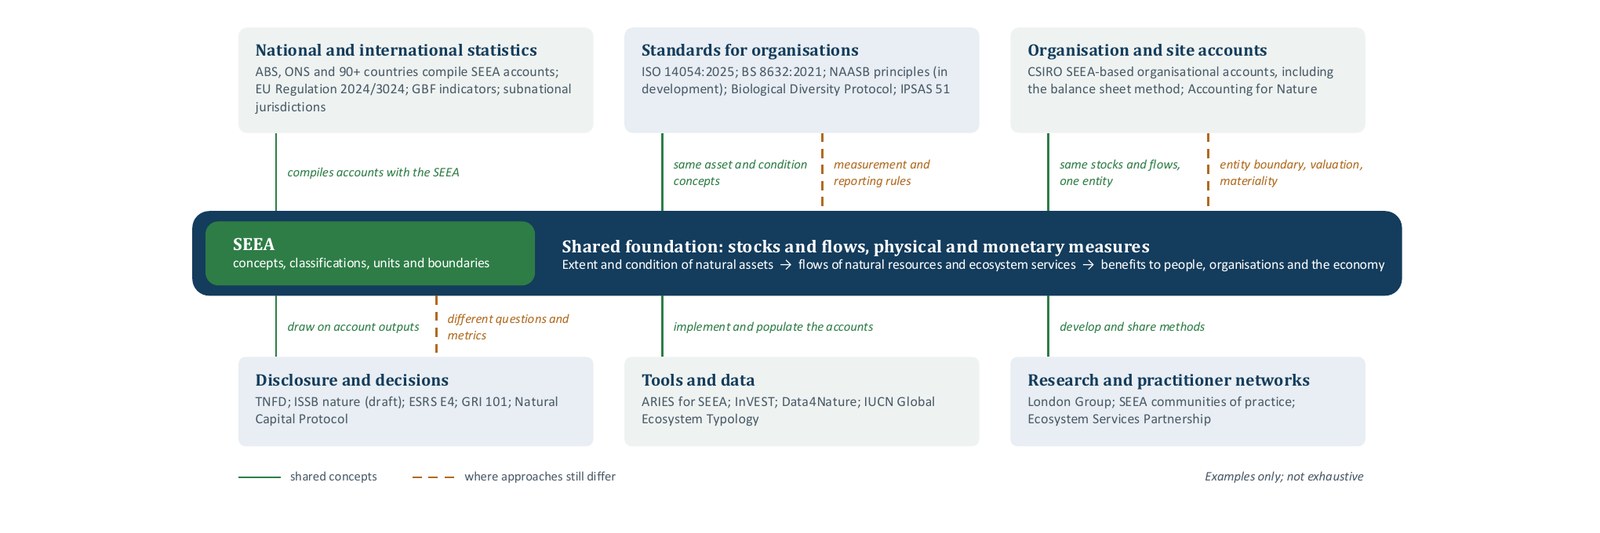
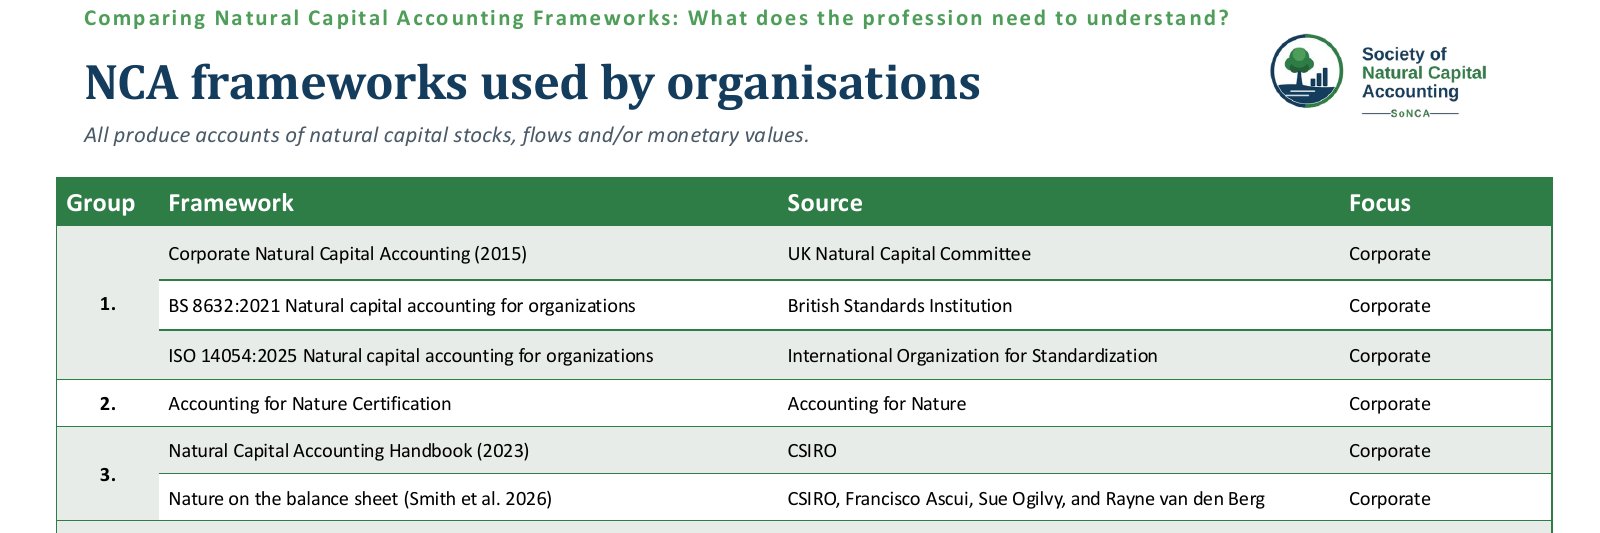
Carl Obst’s question captured a central opportunity explored at the Society of Natural Capital Accounting’s first seminar, “Comparing natural capital accounting frameworks: what does the profession need to understand?”. Users capture information for different purposes, which drives what is presented in a natural capital balance sheet, biodiversity statement of position, or the many other statements described across the seven public and private sector NCA frameworks the group discussed. Greater consistency of data organisation, Carl stressed, could strengthen the usefulness of natural capital accounting across businesses and governments.
The question from Carl grew out of the panel discussion between him, Dr Carter Ingram, Dr Joël Houdet and me, with contributions from Dr Greg Smith and Dr Tony O’Grady. Together, we examined how corporate approaches differ, what they share with the System of Environmental-Economic Accounting, and where further exchange could advance practice.
The discussion showed why this exchange matters. How accounts are constructed affects what users can understand about nature and the decisions they can make.
Different purposes shape different accounts
During the seminar, I proposed that one useful way to understand corporate natural capital accounting (CNCA) frameworks is to group them into one of two approaches. The first seeks to present natural capital accounts alongside, or as a complement to, financial statements. The second seeks to organise and present natural capital information without requiring that relationship to financial statements.
This distinction helps explain design choices among frameworks. Approaches developed to complement financial statements draw on existing concepts of assets, liabilities, control, and statements of position and performance. Approaches that are independent of financial statements tend to aggregate the totality of natural capital values in one statement. Both can support decision-making, and the Society can explore what data feed which business applications or public policy or economic analysis.
Understanding the differences beneath the presentation
The presentation Joël and I made drew on Time to Take Stock, which sets out a working definition of CNCA grounded in changes to natural capital assets and their associated values. This definition formed the basis of Joël’s Unpacking Corporate Natural Capital Accounting paper that applied that definition to published CNCA case studies from different frameworks. It revealed differences in how assets are identified, how condition is measured, and how gains and losses are recorded. These are comparisons of applications, which should be distinguished from conclusions about everything a framework permits or requires.
Consider an ecosystem converted to another land use. An account organised around current land uses may describe that change differently from one that retains the original ecosystem classification and tracks its changing condition. The distinction affects how users interpret losses and subsequent restoration.
“Liability” provides another example. In the Biological Diversity Protocol approach discussed, an accumulated ecological deficit records the gap between current and reference condition without implying a financial settlement obligation. By comparison, Smith et al. (2026), Nature on the balance sheet, links natural capital liabilities to present restoration obligations arising from past events.
These differences reach beyond terminology. They affect the reading of the accounts and the responsibilities readers might infer. Carl noted related discussions within the national accounting community about distinguishing depletion, degradation and other changes. The two communities have substantial scope to learn from each other.
Connecting accounts to business decisions
Carter brought the discussion back to business use. Companies operating in the same landscape often depend on the same natural systems. Spatially explicit accounts can provide a shared information foundation for understanding those dependencies.
A watershed illustrates the opportunity. Several companies may depend on its water supply, water quality and flood regulation. Consistent information about the watershed and changes over time could support risk assessment, investment priorities and collective action.
Carter and colleagues explore these connections in Leveraging natural capital accounting to support businesses with nature-related risk assessments and disclosures. The paper considers how national accounts can provide both an organising framework and information for business applications, while identifying barriers to wider use.
Agriculture, forestry and food offer promising settings in which to demonstrate this utility. Farms and forestry businesses manage natural assets directly, while food companies depend on conditions across their sourcing regions. Testing how accounts improve specific decisions in these sectors could help establish where the benefits are greatest.
The business case still needs demonstration. Tony called for more examples of internal management use, and I raised the need to understand the additional value of accounting relative to its costs and the information businesses already use.
Building understanding through exchange
The seminar built awareness of frameworks that participants might otherwise encounter only through separate publications or professional networks. It also helped clarify why practitioners working with similar concepts can reach different conclusions about account design.
Comparing approaches side by side, as the seminar began to do, would give substance to Carl’s proposal. A shared information foundation could support different outputs while making their relationships easier to understand. Developing it requires careful comparison and continued discussion.
The exchange also made the remaining questions more precise. How should responsibility for ecosystem change be recorded? Where can national data support corporate decisions? What information do managers need that published accounts do not yet provide?
Watch the seminar and bring your questions to the discussion. To share experience or explore ways to engage with the Society, contact inquiries@naturalcapitalaccounting.org.
About the author. John Finisdore is the founder of Sustainable Flows, Washington DC, and a member of the Society of Natural Capital Accounting. Disclosure: John sits on the EU A-Track Advisory Group and the Reporting Group of the Natural Asset Accounting Standards Board (NAASB). The views in this blog are his own and do not represent the views or positions of the Society of Natural Capital Accounting or its committee.